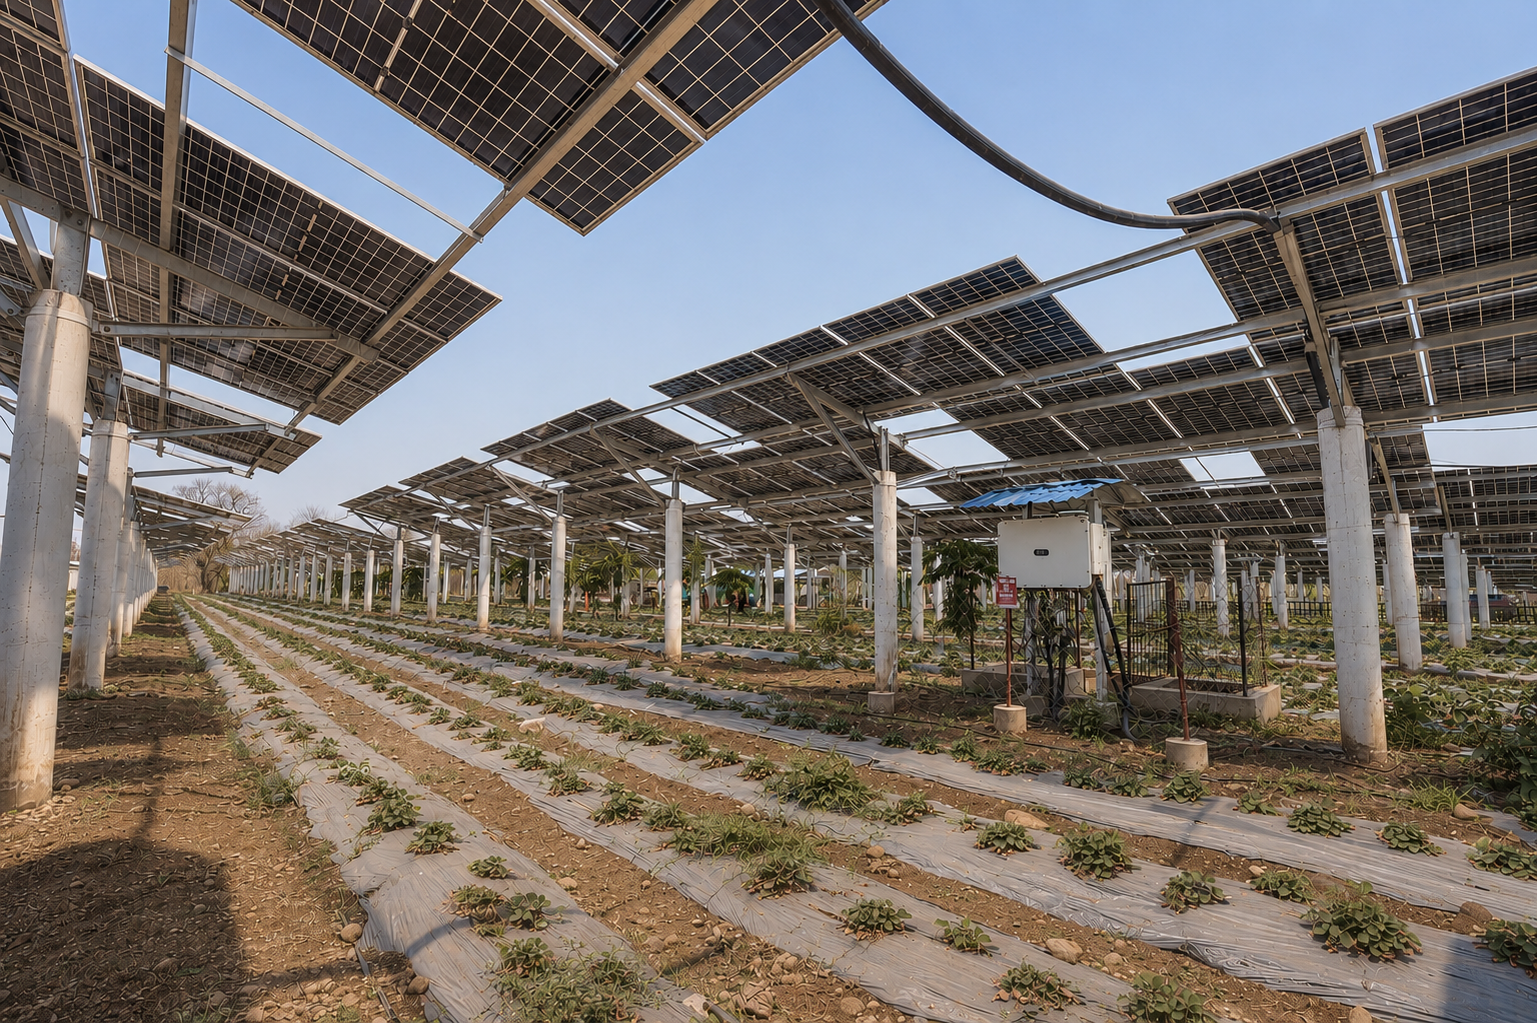
India overtook the United States to become the world’s second-largest market for solar installations in 2025. The country built out close to 50 GW of solar in a year, a feat it is expected to match or even exceed in 2026. And that trend is set to continue, with analysts at Wood Mackenzie forecasting another 526 GW of solar to be added between 2026 and 2035, with projects 5 MW and larger accounting for the largest share. “Inverter demand in the large-scale segment will remain substantial and durable,” said Harshul Kanwar, research analyst at Wood Mackenzie.
The Indian government has supported massive investment in capacity to meet this demand with locally made modules. For the inverters they connect to though, it’s a different story.
“Very little of India’s inverter demand is met by genuinely domestic products,” said Kanwar.
Kanwar noted that while India hosts around 45 GW of inverter manufacturing capacity, this largely only encompasses the final stages of assembly, and is dominated by overseas companies that import the core components from their own manufacturing bases to assemble them into products with only a few locally sourced generic inputs.
Inverter imports to India are subject to the 20% basic customs duty, but the domestic content framework and production-linked incentive scheme that have been key to spurring investments in module manufacturing are not available to the inverter sector. “The policy toolkit for inverters is therefore significantly narrower and provides a softer push toward domestic production than has been applied to modules,” Kanwar explained.
Alongside the more limited policy support, Kanwar further noted that inverter manufacturers face a tougher technical challenge than PV modules. “Inverters are sophisticated power electronics products requiring significant R&D capability, proprietary firmware, and deep supply chain integration. The challenge is considerably greater,” he explained.
Nonetheless, early signs of inverter manufacturing expansion are visible. In the final days of 2025, Waaree Energies announced the start of commercial operations at what is now India’s largest inverter factory in Gujarat. “As India’s renewable energy transition matures, the emphasis is rightly shifting from adding megawatts to ensuring grid-ready, reliable power delivery. The commissioning of our 3.05 GW solar inverter manufacturing facility is a strategic step in that direction,” said Waaree Energies Executive Director Sunil Rathi when announcing the successful ramp-up of the facility.
Representatives for Waaree Energies did not immediately respond to further questions about this facility and the company’s plans in the inverter segment. Kanwar sees it as a notable signal that Indian companies are beginning to see an opportunity, while noting that several local inverter suppliers are positioned strongly in India’s growing residential rooftop PV segment. But he said he expects the market to remain dependent on imports. “Without an ALMM-equivalent policy mandate for inverters, there is no hard regulatory pull compelling project developers to source domestically,” he explained, adding that various overseas companies already have a strong presence in India along with established, cost-optimized manufacturing operations that are difficult for new entrants to compete with.
Technology trends
Since India’s solar market has been driven by very large projects, it has so far favored large central inverters, even as other markets have shifted toward string inverters and the more distributed project layouts they allow. Kanwar estimated that 2025 inverter demand was split roughly 60% to 40% between central and string products. But he said that India has noted the global trend toward string inverters. Maintenance on central inverters is also more complex and comes with the risk of significant downtime and there is a shortage of skilled technicians to carry this out, which is just one of several factors driving project developers in India toward systems based on string layout. “The transition is likely to be gradual given the installed base and the continued strength of central inverter demand in large-scale auction projects, but the direction of travel is towards a greater role for string inverters,” he said.
In the future, though, an expected increase in DC voltage from the current 1,500 V standard to 2,000 V may again favor central inverters. Kanwar said this shift is expected to improve project economics, but proof is still needed that it can be safely and reliably implemented at scale. The shift may also require inverter manufacturers to adopt more advanced silicon carbide or gallium nitride transistor technology, but Kanwar said he expects additional costs from this to be offset by more efficient system layouts requiring fewer combiner boxes.
And as India, along with many other regions, begins to prioritize grid integration to maintain its ambitious installation plans and limit the curtailment of solar output that already threatens the business model for many projects in the country (see pp. 20-21), grid-forming inverters are seeing major demand growth, particularly for energy storage projects. Here, Kanwar noted that it’s relatively simple for manufacturers to add grid-forming features to their products, but further uptake will depend on policy. “Demand for these inverters requires modernized grid codes that allow and financially incentivize inverters to perform grid-forming duties,” he explained.
The post Inverted ambition appeared first on pv magazine Global.
Source link