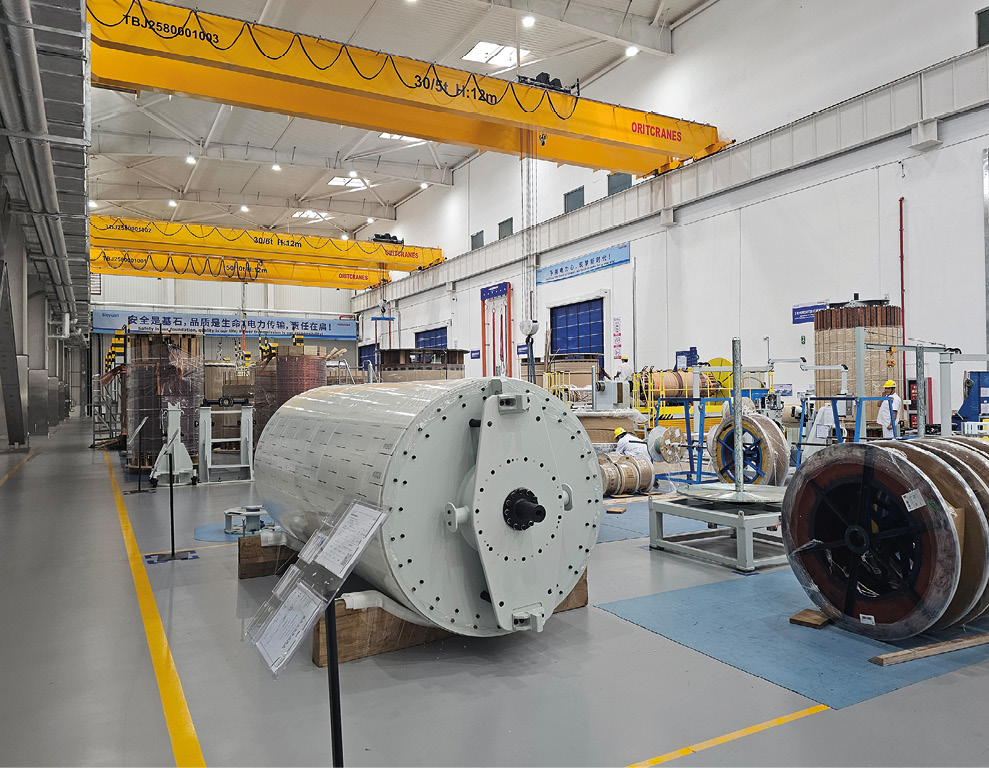
US President Donald Trump signed Executive Order 14421 on Aug. 26, declaring a national emergency to secure the US bulk-power system. The order covers equipment including substation transformers, high-voltage circuit breakers and grid-connected inverters, creating a new national-security screen for foreign-produced bulk-power equipment. The issue was not that equipment available for import suddenly became technically inferior. The rules governing procurement risk had changed, and developers had to react accordingly.
For Levona, this meant reopening the procurement process, qualifying alternative equipment and working against the clock to protect the project’s commercial operation date. Eventually, we identified a US-based engineering, procurement and construction (EPC) supply path with a main power transformer and breaker available on a more favorable schedule than a new manufacturing slot. It solved a schedule problem, but at a cost roughly 40% above the solution from China we had been evaluating before the policy change.
That was not the only repricing event affecting US solar in 2026. In August, a Section 232 action on polysilicon and derivative products changed the module procurement environment. Module proposals that had been around $0.27/W for our project moved into the low-$0.40/W range in some cases. The FCC’s August modification of the Covered List for power inverters added another compliance screen. Each event was manageable on its own. Together, they forced repeated revisions to project capex and procurement strategy.
PPA pricing
Recent exclusive power purchase agreement (PPA) negotiations with a large technology-sector power buyer have made the sensitivity of the model particularly clear. We have been updating equipment costs, transmission requirements, nodal and capture-price assumptions, and contract risk allocation as the market moves. One lesson that has become difficult to ignore is that fixed revenue against floating costs and evolving risk allocation can be one of the most dangerous positions for a developer in today’s power market.
This doesn’t mean developers should simply wait to sign contracts. Preserving commercial flexibility is expensive. Development capital continues to be spent while revenue certainty remains unresolved. But in a market where modules, high-voltage equipment, transmission obligations and contract risk can move within months, locking in a PPA too early can crystallize a revenue assumption while the cost structure underneath it is still changing.
The market side is changing as well. Ascend Analytics’ July 2026 outlook for the Texas ERCOT grid expects projects that miss federal tax incentives to require materially higher green premiums and identifies durable value for projects that preserve tax-credit eligibility. Its forecast also shows renewable development slowing as tax credits phase out, while implied solar renewable energy certificate (REC) values rise sharply around the transition. In Ascend’s forecast, solar REC values move from low-single-digit dollars per megawatt-hour today to above $20/MWh around the early 2030s before moderating later. That is a market signal that the value of qualifying renewable supply may be changing materially.
The One Big Beautiful Bill Act makes the distinction especially important. For applicable wind and solar projects, the new termination rules generally make the deadline of July 4, 2026, for beginning construction critical for projects expected to enter service after 2027. That creates two increasingly different groupings: projects that established construction in time and can preserve access to clean-electricity tax credits, subject to the applicable requirements, and later projects that may have to reach commercial viability without the same economics.
For power to be delivered in 2029, 2030, 2031 and 2032, that difference could be decisive. The number of projects combining tax-credit eligibility, advanced interconnection, viable transmission, site control, engineering maturity, qualified equipment and a credible path to commercial operations is finite. Every project that fails on permitting, financing, interconnection, procurement or continuity reduces that pool further.
At the same time, demand is moving in the opposite direction. Ascend estimates that more than 80% of new load that has filed with ERCOT transmission service providers will not find matching new supply by 2030. Data centers account for a large share of expected growth, although Ascend also highlights substantial attrition between announced, approved and actually energized loads. The market is therefore confronting two forms of scarcity at once: not every announced load will materialize, and not every megawatt in a generation queue will become financeable electricity.
That matters for how buyers and developers discuss PPA pricing. A project should not be compared only with the price it could have offered six months ago. It should also be compared with the replacement cost of the next financeable megawatt-hour. If the replacement project has no preserved tax-credit position, a later interconnection date, higher equipment costs, unresolved transmission exposure and a less certain COD, a higher-priced advanced project may still represent the lower-risk and lower-cost option for a buyer that actually needs power before 2030.
The US solar industry spent the last decade proving that it could reduce generation costs at remarkable speed. The next phase may be defined by the ability to preserve optionality while policy, procurement and market rules move underneath projects that take years to develop.
For developers, that requires technical discipline, capital and patience. For large power buyers, the relevant benchmark may no longer be yesterday’s solar PPA price. It may be the replacement cost of the next financeable megawatt-hour.
The post When the rules change faster than the project appeared first on pv magazine Global.
Source link